Life Insurance in Tyler, Built Around the Fine Print
We help clients in Tyler, Whitehouse and Lindale choose and set up life insurance: term and permanent policies, final expense and mortgage protection plans, and retirement income planning. The term gets matched to your debts, the beneficiary line to your wishes, and every rider is checked so you know it applies.
Serving Tyler and Nearby Towns
Our clients live and work in Tyler and in the towns around it, including Whitehouse, Chandler, Lindale and Bullard, along with Hideaway and Shadybrook. Since the conversations, quotes and paperwork mostly happen by phone, the drive between towns never slows anything down.
- Tyler
- Whitehouse
- Chandler
- Lindale
- Bullard
- Hideaway
- Shadybrook
If you are outside these towns but still in East Texas, give us a call and we can tell you whether we can help.
Life Insurance and Retirement Planning We Handle
Term life insurance covers a set number of years at a fixed premium, and it fits debts and working years that have an end date. Whole life insurance and universal life insurance last for life and build cash value, though they handle premiums and interest very differently. Final expense insurance and mortgage protection insurance are narrower policies with one clear job each. Retirement income planning looks at the other side of the ledger: turning savings into steady monthly income you cannot outlive.
Term Life Insurance
Level-premium coverage for 10 to 30 years, sized to your debts and dependents, with beneficiaries and conversion deadlines checked line by line.
Universal Life Insurance
Flexible permanent coverage with adjustable premiums, set up with a funding level and death benefit option that keep the policy from lapsing later.
Retirement Income Planning
We map Social Security, pension elections and life insurance cash value year by year to find the gaps in your retirement income and show ways to close them.
Whole Life Insurance
Permanent coverage with level premiums and cash value, with the riders, dividend election and beneficiary wording set up correctly from the first day.
Mortgage Protection
Life coverage built around your mortgage balance and payoff date, so your family can clear the loan or keep paying it on their own terms.
Final Expense Insurance
A smaller whole life policy meant to cover funeral costs, final medical bills and small debts, with the waiting period and beneficiary details checked before you sign.
About Life Insurance Tyler
We are a life insurance agency working with clients across Tyler and East Texas. Our work is helping people put coverage in place that still does its job ten or twenty years after the signature, which comes down to details most buyers never get shown.
We explain the parts of a policy that decide how it performs: the contestability period, the grace period for a missed payment, how a universal life policy's cash value reacts when interest credits drop, and why a beneficiary form overrides a will. You should know what you own and why each line is there.
How Getting Coverage Works
From the first call to the delivered policy, each step has a clear purpose. Most of the work happens over the phone, with your paperwork reviewed line by line.
- 1
A conversation about what you need
We ask about your debts, income, dependents, existing coverage through work and what you want the policy to do. That tells us the face amount and term that fit.
- 2
Quotes compared side by side
We show you a few options with the premium, term, riders and conversion terms for each. You see the tradeoffs before you choose anything.
- 3
Application and underwriting
We complete the application with you so the health answers are accurate, since a misstated answer can give the carrier grounds to contest a claim. Depending on the carrier and amount, underwriting may include a short paramedical exam, a prescription history check and a phone interview.
- 4
Policy delivery review
Once the carrier issues the contract, we read it alongside you and check the named beneficiaries, the riders and the premium against the application. If anything differs from what you asked for, the free-look window lets you cancel.
What Moves a Life Insurance Premium
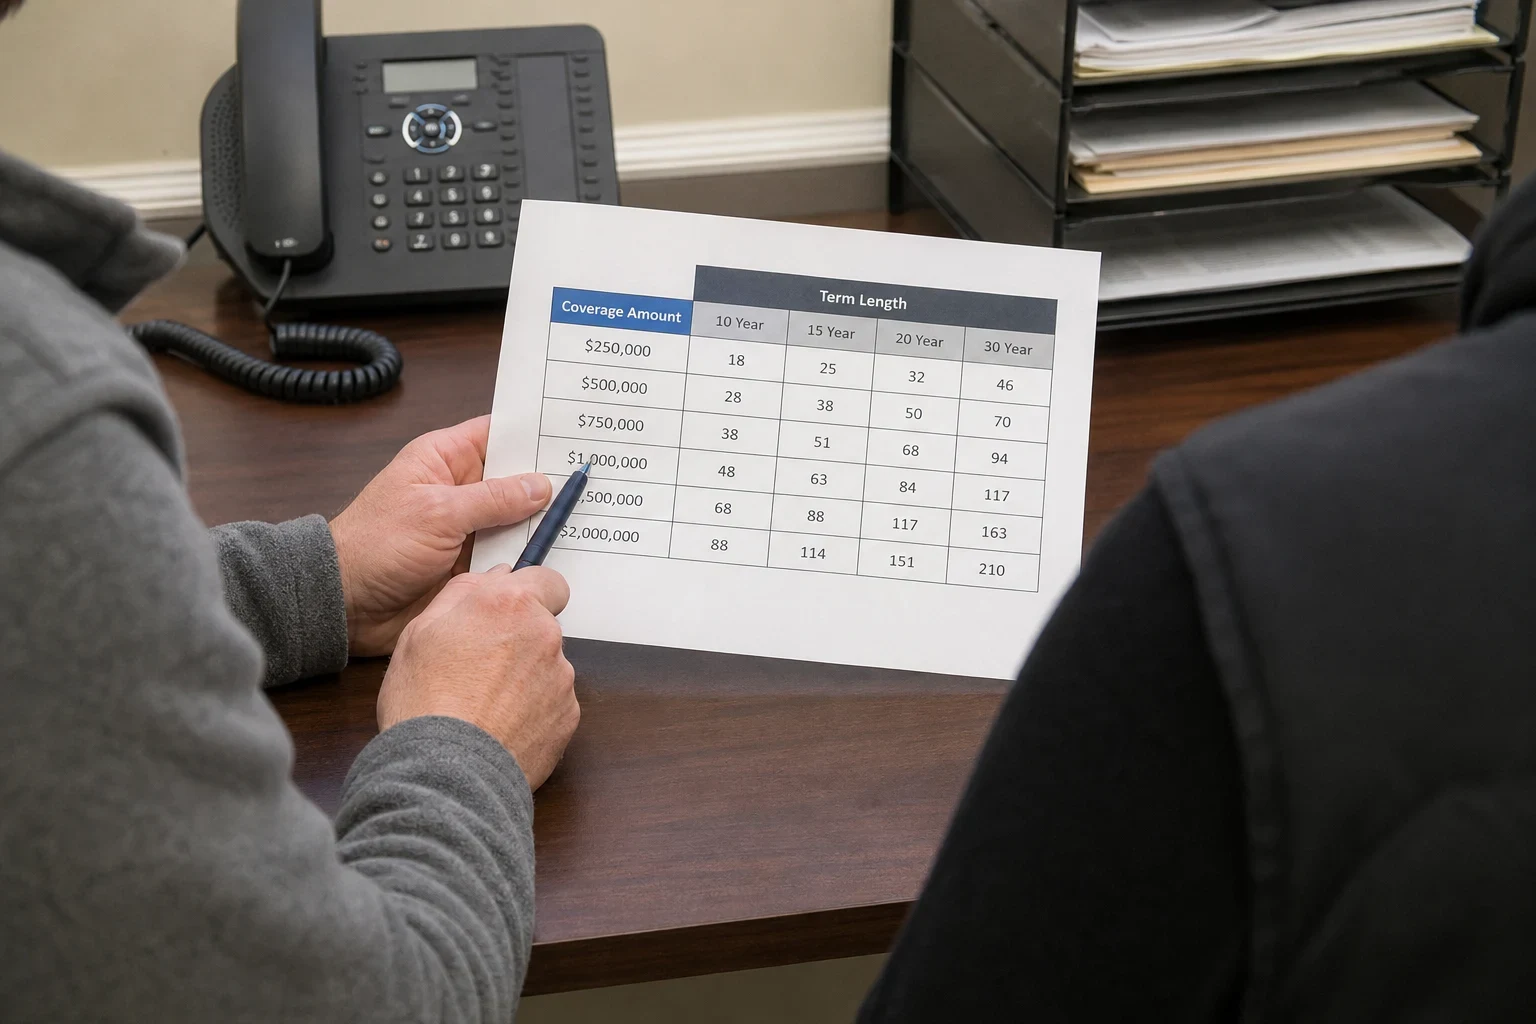
Carriers price a policy by weighing how likely a claim is during the years it stays in force. A short list of factors does most of that work, and you can influence some of them. These are the ones underwriters weigh first.
We give you quotes by phone after we understand your health, goals and budget, and we explain each figure before you apply. Final pricing is set by the carrier once underwriting is complete.
- Age at application
- Premiums are set by your age on the day the policy is issued, and many carriers count your nearest birthday. Applying a few months earlier can sometimes put you in a lower age band.
- Health and underwriting class
- Blood pressure, cholesterol, build, prescriptions and family history place you in a rating class. Moving one class up or down changes the premium more than almost anything else.
- Tobacco and nicotine use
- Cigarettes, vaping, chewing tobacco and even occasional cigars usually move you into tobacco rates. Most carriers look for a set period free of nicotine before offering non-tobacco pricing.
- Coverage amount and term length
- Every added dollar of face amount and every added year of term adds to what you pay. We size both to the debts and income they are meant to replace, so no part of the premium buys coverage without a job to do.
- Policy type
- Term coverage is the lowest cost per dollar of protection. Whole life and universal life cost more because part of each premium funds cash value and lifetime coverage.
- Riders added
- Each rider carries its own charge. A few are worth the cost for most clients, while others duplicate protection you already have through work or another policy.
Why Clients Work With Us
Most policy problems do not show up on the day you sign. They show up years later, in a clause nobody read or a form nobody updated, so that is where we spend our time.
- 01
Term length matched to real dates
We line the term up with the dates that matter, like the last mortgage payment or the year your youngest finishes school. A 20-year term that ends three years before your loan does leaves a gap at exactly the wrong time.
- 02
Beneficiary lines written precisely
We name primary and contingent beneficiaries by full legal name and set the percentages so they add up. A vague entry like "my children" or an outdated ex-spouse can send proceeds through probate or to the wrong person.
- 03
Riders you can explain
Waiver of premium, accelerated benefit, conversion and child riders each have their own trigger and cost. We tell you what each one does in plain terms and leave off the ones you do not need.
- 04
Conversion cutoffs written down early
A conversion privilege lets you trade term coverage for a permanent policy with no fresh health questions, and each carrier sets its own cutoff by age or policy year. We record that cutoff for you when the policy is issued, so the option is still open if your health changes later.
- 05
A straight call on term versus permanent
When a term policy handles the need, that is what we recommend, even though a permanent policy would cost you more. Whole life and universal life earn their place for specific goals, like a lifelong dependent or an estate cost, and we tell you which goals those are.
Questions Clients Ask About Life Insurance
Something not covered here? (903) 420-9220
How much life insurance do I actually need?
A common starting point is enough to pay off your debts, cover final costs and replace several years of income for the people who depend on you. We add up the mortgage balance, other loans, future school costs and income needs, then subtract savings and any coverage through work. The result is a number based on your situation, not a rule of thumb.
Should I buy term life or whole life?
Term life fits most clients whose need has an end date, like a mortgage or children still in school, because it gives the most coverage for the premium. Whole life fits permanent needs such as estate planning, a lifelong dependent or leaving a set amount regardless of when you pass. Some clients use both: a large term policy for the working years and a smaller permanent one for life.
Will I need a medical exam?
Not always. Each carrier draws its own line based on your age and the face amount you apply for. Many smaller policies are approved from prescription records and medical database checks alone. Higher amounts typically call for a brief paramedical visit, where an examiner checks blood pressure and collects blood and urine samples, usually at a time and place you pick.
Can I get coverage with a health condition?
Often, yes. Conditions like controlled diabetes, high blood pressure or a past cancer are rated differently by different carriers, so where you apply matters. For clients with serious health issues, final expense insurance with simplified underwriting can still provide coverage.
Isn't the life insurance from my job enough?
Group coverage through work is often one or two times your salary, which usually falls short of what a family needs. It also typically ends or changes when you leave the job. An individual policy stays with you no matter where you work.
Can I change my beneficiary later?
Yes. A revocable beneficiary can usually be changed whenever you like by sending the insurer a change form. Good moments to look at it again are after a wedding, a divorce, a new child or a death in the family. Whatever designation the insurer holds decides who gets paid, even when your will names someone else.
What happens if I miss a premium payment?
Most policies have a grace period, often around a month, during which coverage stays in force. If the premium is not paid by the end of it, a term policy can lapse, and a universal life policy may draw from its cash value until that runs out. We explain how your specific policy handles this before you sign.
Get Coverage Set Up Correctly the First Time
Tell us what you want your policy to protect, and we will walk through the term, riders and beneficiary details with you. There is no obligation to apply.